|
We recently issued a report that analyzed statistical trends for the major functions of the IRS’s Tax Exempt and Government Entities Division. But did you know that every year, we also do a deep dive into IRS enforcement statistics? It's full of data that provide taxpayers and stakeholders with information about how the IRS focuses its compliance resources and the impact of those resources on revenue and compliance over time.
Trends in Compliance Activities Through Fiscal Year 2025
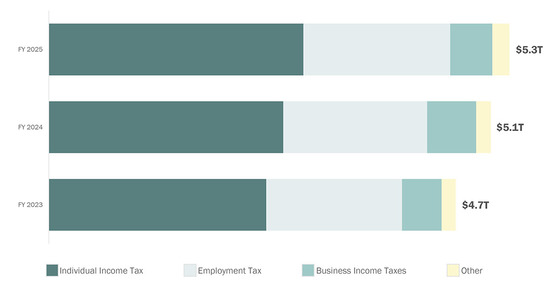
Taxpayers paid the IRS $5.3 trillion in Fiscal Year (FY) 2025, up 13.2 percent from FY 2023 and the highest amount ever, without adjusting for inflation. Enforcement revenue reached a record $98.7 billion in FY 2024 before declining to $93.8 billion in FY 2025, primarily due to a 35 percent decline in examination revenue.
Total Federal Tax Revenue Paid to the IRS Was at a Historic High in FY 2025
 After substantial hiring in FY 2023 and 2024, the IRS lost approximately 27 percent of its Examination and Collection staff from FY 2024 to FY 2025. The effects of these reductions are expected to become more apparent over time.
Annual appropriations remained $12.3 billion from FY 2023 through FY 2025, including approximately $5.2 billion to $5.4 billion annually for enforcement. The IRS also exhausted $3.8 billion in supplemental Inflation Reduction Act enforcement funding as of December 31, 2025.
Collection revenue increased 17 percent from FY 2023 to FY 2025, offsetting declines in other enforcement revenue categories, primarily due to resumed automated collection notices. The IRs sent approximately 3.2 million notices to individual nonfilers in FY 2025, compared with none in FY 2023.
Examination revenues increased 41 percent from FY 2023 to 2024 before declining 35 percent in FY 2025, coinciding with increased staffing followed by workforce reductions. From FY 2024 to 2025, examinations started for individual returns declined 30 percent, including a 27 percent decline for taxpayers with incomes over $400,000.
For more stats:
Having trouble viewing this email? View it as a Web page.
|