|
Please click here to view this email in your web browser.
The Supreme Court of the United States released one (1) opinion on Friday, February 20. The following is the syllabus for that opinion prepared by the Reporter of Decisions of the Supreme Court of the United States. The Reporter of Decisions is the official charged with editing and publishing the Court's opinions both when announced and when they are published in permanent bound volumes of the United States Reports. The syllabus constitutes no part of the opinion of the Court, but has been prepared for the convenience of the reader.
CERTIORARI BEFORE JUDGMENT TO THE UNITED STATES COURT OF APPEALS FOR THE DISTRICT OF COLUMBIA CIRCUIT
No. 24–1287. Argued November 5, 2025—Decided February 20, 2026*
*Together with No. 25–250, Trump v. V.O.S. Selections, Inc.
Questions Presented
1. Whether the International Emergency Economic Powers Act (IEEPA), Pub. L. No. 95-
223, Tit. II, 91 Stat. 1626, authorizes the tariffs imposed by President Trump pursuant to the
national emergencies declared or continued in Proclamation 10,886 and Executive Orders
14,157, 14,193, 14,194, 14,195, and 14,257, as amended.
2. If IEEPA authorizes the tariffs, whether the statute unconstitutionally delegates legislative authority to the President.
CERT. GRANTED 9/9/2025
Holding
The International Emergency Economic Powers Act does not authorize the President to impose tariffs.
Judgment
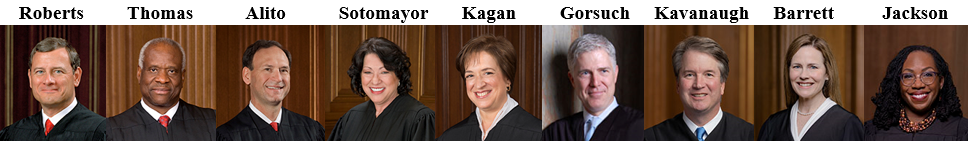
Vacated and remanded on February 20, 2026 in an opinion entered by Chief Justice Roberts. Justices Gorsuch and Barrett entered a concurring opinion. Justices Kagan, Sotomayor and Jackson entered opinions concurring in part and concurring in the judgment. Justice Thomas entered a dissenting opinion. Justices Kavanaugh, Thomas, and Alito entered an additional dissenting opinion.
Syllabus
The question presented is whether the International Emergency Economic Powers Act (IEEPA) authorizes the President to impose tariffs. See 91 Stat. 1626. Shortly after taking office, President Trump sought to address two foreign threats: the influx of illegal drugs from Canada, Mexico, and China, Presidential Proclamation No. 10886, 90 Fed. Reg.8327; Exec. Order No. 14193, 90 Fed. Reg. 9113; Exec. Order No. 14194, 90 Fed. Reg. 9117; Exec. Order No. 14195, 90 Fed. Reg. 9121, and “large and persistent” trade deficits, Exec. Order No. 14257, 90 Fed. Reg. 15041. The President determined that the drug influx had “created a public health crisis,” 90 Fed. Reg. 9113, and that the trade deficits had “led to the hollowing out” of the American manufacturing base and “undermined critical supply chains,” id., at 15041. The President declared a national emergency as to both threats, deeming them “unusual and extraordinary,” and invoked his authority under IEEPA to respond.
He imposed tariffs to deal with each threat. As to the drug trafficking tariffs, the President imposed a 25% duty on most Canadian and Mexican imports and a 10% duty on most Chinese imports. Id., at 9114, 9118, 9122–9123. As to the trade deficit (“reciprocal”) tariffs, the President imposed a duty “on all imports from all trading partners” of at least 10%, with dozens of nations facing higher rates. Id., at 15045, 15049. Since imposing each set of tariffs, the President has issued several increases, reductions, and other modifications.
Petitioners in Learning Resources and respondents in V.O.S. Selections filed suit, alleging that IEEPA does not authorize the reciprocal or drug trafficking tariffs. The Learning Resources plaintiffs—two small businesses—sued in the United States District Court for the District of Columbia. That court denied the Government’s motion to transfer the case to the United States Court of International Trade (CIT) and granted the plaintiffs’ motion for a preliminary injunction, concluding that IEEPA did not grant the President the power to impose tariffs. The V.O.S. Selections plaintiffs—five small businesses and 12 States—sued in the CIT. That court granted summary judgment for the plaintiffs. And the Federal Circuit, sitting en banc, affirmed in relevant part, concluding that IEEPA’s grant of authority to “regulate . . . importation” did not authorize the challenged tariffs, which “are unbounded in scope, amount, and duration.” 149 F. 4th 1312, 1338. The Government filed a petition for certiorari in V.O.S. Selections, and the Learning Resources plaintiffs filed a petition for certiorari before judgment. The Court granted the petitions and consolidated the cases.
Held: IEEPA does not authorize the President to impose tariffs.
The judgment in No. 24–1287 is vacated, and the case is remanded with instructions to dismiss for lack of jurisdiction; the judgment in No. 25–250 is affirmed. No. 24–1287, 784 F. Supp. 3d 209, vacated and remanded; No. 25–250, 149 F. 4th 1312, affirmed.
THE CHIEF JUSTICE delivered the opinion of the Court with respect to Parts I and II–A–1:
Article I, Section 8, of the Constitution specifies that “The Congress shall have Power To lay and collect Taxes, Duties, Imposts and Excises.” The Framers recognized the unique importance of this taxing power—a power which “very clear[ly]” includes the power to impose tariffs. Gibbons v. Ogden, 9 Wheat. 1, 201. And they gave Congress “alone . . . access to the pockets of the people.” The Federalist No. 48,
p. 310 (J. Madison). The Framers did not vest any part of the taxing power in the Executive Branch. See Nicol v. Ames, 173 U. S. 509, 515.
The Government thus concedes that the President enjoys no inherent authority to impose tariffs during peacetime. It instead relies exclusively on IEEPA to defend the challenged tariffs. It reads the words “regulate” and “importation” to effect a sweeping delegation of Congress’s power to set tariff policy—authorizing the President to impose tariffs of unlimited amount and duration, on any product from any country. 50 U. S. C. §1702(a)(1)(B). Pp. 5–7.
THE CHIEF JUSTICE, joined by JUSTICE GORSUCH and JUSTICE BARRETT, concluded in Part II–A–2:
The Court has long expressed “reluctan[ce] to read into ambiguous statutory text” extraordinary delegations of Congress’s powers. West Virginia v. EPA, 597 U. S. 697, 723 (quoting Utility Air Regulatory Group v. EPA, 573 U. S. 302, 324). In several cases described as involving “major questions,” the Court has reasoned that “both separation of powers principles and a practical understanding of legislative intent” suggest Congress would not have delegated “highly consequential power” through ambiguous language. Id., at 723–724. These considerations apply with particular force where, as here, the purported delegation involves the core congressional power of the purse. Congressional practice confirms as much. When Congress has delegated its tariff powers, it has done so in explicit terms and subject to strict limits.
Against that backdrop of clear and limited delegations, the Government reads IEEPA to give the President power to unilaterally impose unbounded tariffs and change them at will. That view would represent a transformative expansion of the President’s authority over tariff policy. It is also telling that in IEEPA’s half century of existence, no President has invoked the statute to impose any tariffs, let alone tariffs of this magnitude and scope. That “ ‘lack of historical precedent,’ coupled with the breadth of authority” that the President now claims, suggests that the tariffs extend beyond the President’s “legitimate reach.” National Federation of Independent Business v. OSHA, 595 U. S. 109, 119 (quoting Free Enterprise Fund v. Public Company Accounting Oversight Bd., 561 U. S. 477, 505). The “ ‘economic and political significance’ ” of the authority the President has asserted likewise “provide[s] a ‘reason to hesitate before concluding that Congress’ meant to confer such authority.” West Virginia, 597 U. S., at 721 (quoting FDA v. Brown & Williamson Tobacco Corp., 529 U. S. 120, 159–160). The stakes here dwarf those of other major questions cases. And as in those cases, “a reasonable interpreter would [not] expect” Congress to “pawn[]” such a “big-time policy call[] . . . off to another branch.” Biden v. Nebraska, 600 U. S. 477, 515 (BARRETT, J., concurring).
There is no exception to the major questions doctrine for emergency statutes. Nor does the fact that tariffs implicate foreign affairs render the doctrine inapplicable. The Framers gave “Congress alone” the power to impose tariffs during peacetime. Merritt v. Welsh, 104 U. S. 694, 700. And the foreign affairs implications of tariffs do not make it any more likely that Congress would relinquish its tariff power through vague language, or without careful limits. Accordingly, the President must “point to clear congressional authorization” to justify his extraordinary assertion of that power. Nebraska, 600 U. S., at 506 (internal quotation marks omitted). He cannot. Pp. 7–13.
THE CHIEF JUSTICE delivered the opinion of the Court with respect to Part II–B, concluding:
(a) IEEPA authorizes the President to “investigate, block during the pendency of an investigation, regulate, direct and compel, nullify, void, prevent or prohibit . . . importation or exportation.” §1702(a)(1)(B). Absent from this lengthy list of specific powers is any mention of tariffs or duties. Had Congress intended to convey the distinct and extraordinary power to impose tariffs, it would have done so expressly, as it consistently has in other tariff statutes.
The power to “regulate . . . importation” does not fill that void. The term “regulate,” as ordinarily used, means to “fix, establish, or control; to adjust by rule, method, or established mode; to direct by rule or restriction; to subject to governing principles or laws.” Black’s Law Dictionary 1156. The facial breadth of this definition places in stark relief what ”regulate” is not usually thought to include: taxation. Many statutes grant the Executive the power to “regulate.” Yet the Government cannot identify any statute in which the power to regulate includes the power to tax. The Court is therefore skeptical that in IEEPA—and IEEPA alone—Congress hid a delegation of its birth-right power to tax within the quotidian power to “regulate.”
While taxes may accomplish regulatory ends, it does not follow that the power to regulate includes the power to tax as a means of regulation. Indeed, when Congress addresses both the power to regulate and the power to tax, it does so separately and expressly. That it did not do so here is strong evidence that “regulate” in IEEPA does not include taxation.
A contrary reading would render IEEPA partly unconstitutional. IEEPA authorizes the President to “regulate . . . importation or exportation.” §1702(a)(1)(B). But taxing exports is expressly forbidden by the Constitution. Art. I, §9, cl. 5.
The “neighboring words” with which “regulate” “is associated” also suggest that Congress did not intend for “regulate” to include the revenue-raising power. United States v. Williams, 553 U. S. 285, 294. Each of the nine verbs in §1702(a)(1)(B) authorizes a distinct action a President might take in sanctioning foreign actors or controlling domestic actors engaged in foreign commerce, as Presidential practice confirms. And none of the listed authorities includes the distinct and extraordinary power to raise revenue—a power which no President has ever found in IEEPA. Pp. 14–16.
(b) Several arguments marshaled in response are unpersuasive. First, the contention that IEEPA confers the power to impose tariffs because early commentators and the Court’s cases discuss tariffs in the context of the Commerce Clause answers the wrong question. The question is not whether tariffs can ever be a means of regulating commerce. It is instead whether Congress, when conferring the power to “regulate . . . importation,” gave the President the power to impose tariffs at his sole discretion. And Congress’s pattern of usage is plain: When Congress grants the power to impose tariffs, it does so clearly and with careful constraints. It did neither in IEEPA.
Second, the argument that “regulate” naturally includes tariffs because the term lies between two poles in IEEPA—“compel” on the affirmative end and “prohibit” on the negative end—is unavailing. Although tariffs may be less extreme than an outright compulsion orprohibition, it does not follow that tariffs lie on the spectrum between those poles; they are different in kind, not degree, from the other authorities in IEEPA. Tariffs operate directly on domestic importers to raise revenue for the Treasury and are “very clear[ly] . . . a branch of the taxing power.” Gibbons, 9 Wheat., at 201. Thus, they fall outside the spectrum entirely.
Third, the argument based on IEEPA’s predecessor, the Trading with the Enemy Act (TWEA), and the Court of Customs and Patent Appeals’ decision in United States v. Yoshida Int’l, Inc., 526 F. 2d 560, cannot bear the weight placed on it. A single, expressly limited opinion from a specialized intermediate appellate court does not establish a well-settled meaning that the Court can assume Congress incorporated into IEEPA.
Fourth, the historical argument based on the Court’s wartime precedents fails. Those precedents are facially inapposite, as all agree the President lacks inherent peacetime authority to impose tariffs. And the attenuated chain of inferences from wartime precedents through multiple iterations of TWEA to IEEPA cannot support—much less clearly support—a reading of IEEPA that includes the distinct power to impose tariffs.
Finally, arguments relying on this Court’s precedents lack merit. Federal Energy Administration v. Algonquin SNG, Inc., 426 U. S. 548, bears little on the meaning of IEEPA. Section 232(b) of the Trade Expansion Act of 1962 contains sweeping, discretion-conferring language that IEEPA does not contain, and the explicit reference to duties in Section 232(a) renders it natural for Section 232(b) itself to authorize duties. Nor does Dames & Moore v. Regan, 453 U. S. 654, offer support because that case was exceedingly narrow, did not address the President’s power to “regulate,” and did not involve tariffs at all. Pp. 16–20.
JUSTICE KAGAN, joined by JUSTICE SOTOMAYOR and JUSTICE JACKSON, agreed that IEEPA does not authorize the President to impose tariffs, but concluded that the Court need not invoke the major questions doctrine because the ordinary tools of statutory interpretation amply support that result. Pp. 1–7.
JUSTICE JACKSON would also consult legislative history—in particular, the House and Senate Reports that accompanied IEEPA and its predecessor statute, TWEA—to determine that Congress did not intend for IEEPA to authorize the Executive to impose tariffs. Pp. 1–5.
ROBERTS, C. J., announced the judgment of the Court and delivered the opinion of the Court with respect to Parts I, II–A–1, and II–B, in which SOTOMAYOR, KAGAN, GORSUCH, BARRETT, and JACKSON, JJ., joined, and an opinion with respect to Parts II–A–2 and III, in which GORSUCH and BARRETT, JJ., joined. GORSUCH, J., and BARRETT, J., filed concurring opinions. KAGAN, J., filed an opinion concurring in part and concurring in the judgment, in which SOTOMAYOR and JACKSON, JJ., joined. JACKSON, J., filed an opinion concurring in part and concurring in the judgment. THOMAS, J., filed a dissenting opinion. KAVANAUGH J., filed a dissenting opinion, in which THOMAS and ALITO, JJ., joined.
Case Information
SCOTUSblog Coverage
-
Supreme Court strikes down tariffs (Amy Howe, February 20, 2026)
-
When will we get the tariffs ruling? (Amy Howe, January 29, 2026)
-
No tariff opinion (Mark Walsh, January 9, 2026)
-
How the tariffs could be refunded if the court sides against Trump (Amy Howe, December 18, 2025)
-
The who’s and what’s of presidential power (Adam White, December 5, 2025)
-
No Executive Taxation Without Clear Legislative Authorization (Akhil and Vikram Amar, November 7, 2025)
-
In tariff cases, verbs rather than major pronouncements about presidential power give the court the off-ramp it’s looking for (Abbe R. Gluck, November 7, 2025)
-
Trump’s tariffs: from dollars to donuts (Mark Walsh, November 5, 2025)
-
Court appears dubious of Trump’s tariffs (Amy Howe, November 5, 2025)
-
The tariffs case and whether amicus briefs matter (Erwin Chemerinsky, November 4, 2025)
-
The other arguments in Trump’s tariffs case (Amy Howe, November 4, 2025)
-
President Trump’s tariffs v. the Supreme Court’s duties (Adam White, November 3, 2025)
-
Trump’s tariffs to face Supreme Court scrutiny (Amy Howe, October 30, 2025)
-
Oral argument live blog for Wednesday, November 5 (SCOTUSblog, October 24, 2025)
-
Small businesses and states ask court to uphold orders striking down Trump’s tariffs (Amy Howe, October 21, 2025)
-
The Trump docket (Erwin Chemerinsky, October 7, 2025)
-
Trump administration urges Supreme Court to uphold tariffs (Amy Howe, September 19, 2025)
-
Supreme Court announces it will hear challenges to Trump’s tariffs on Nov. 5 (Amy Howe, September 18, 2025)
-
The Supreme Court, tariffs, and judicial consistency (Erwin Chemerinsky, September 15, 2025)
-
Supreme Court agrees to decide the fate of Trump’s tariffs (Amy Howe, September 9, 2025)
-
Trump administration brings tariffs case to Supreme Court (Amy Howe, September 4, 2025)
-
What the Trump administration wants from the Supreme Court this term (Kelsey Dallas, September 3, 2025)
-
The Supreme Court and Trump’s tariffs: an explainer (Amy Howe, August 25, 2025)
-
Businesses challenge Trump’s tariffs before Supreme Court (Amy Howe, June 17, 2025)
SUBSCRIBER SERVICES:
Manage Preferences | Unsubscribe | Help
Contact a librarian
|